
User-first design that actually helps
Everyday borrowers want clarity and speed — no fuss, no jargon. That’s where didi finanzas comes in, focusing on simple onboarding and a clear credit line rather than long paperwork. Based on conversations with drivers and small-business owners in Mexico City, the appeal is obvious: fast access to revolving credit and digital wallet features that slot into daily life. The product feels built around someone who needs working capital now, not six months from now.
How it works in real terms
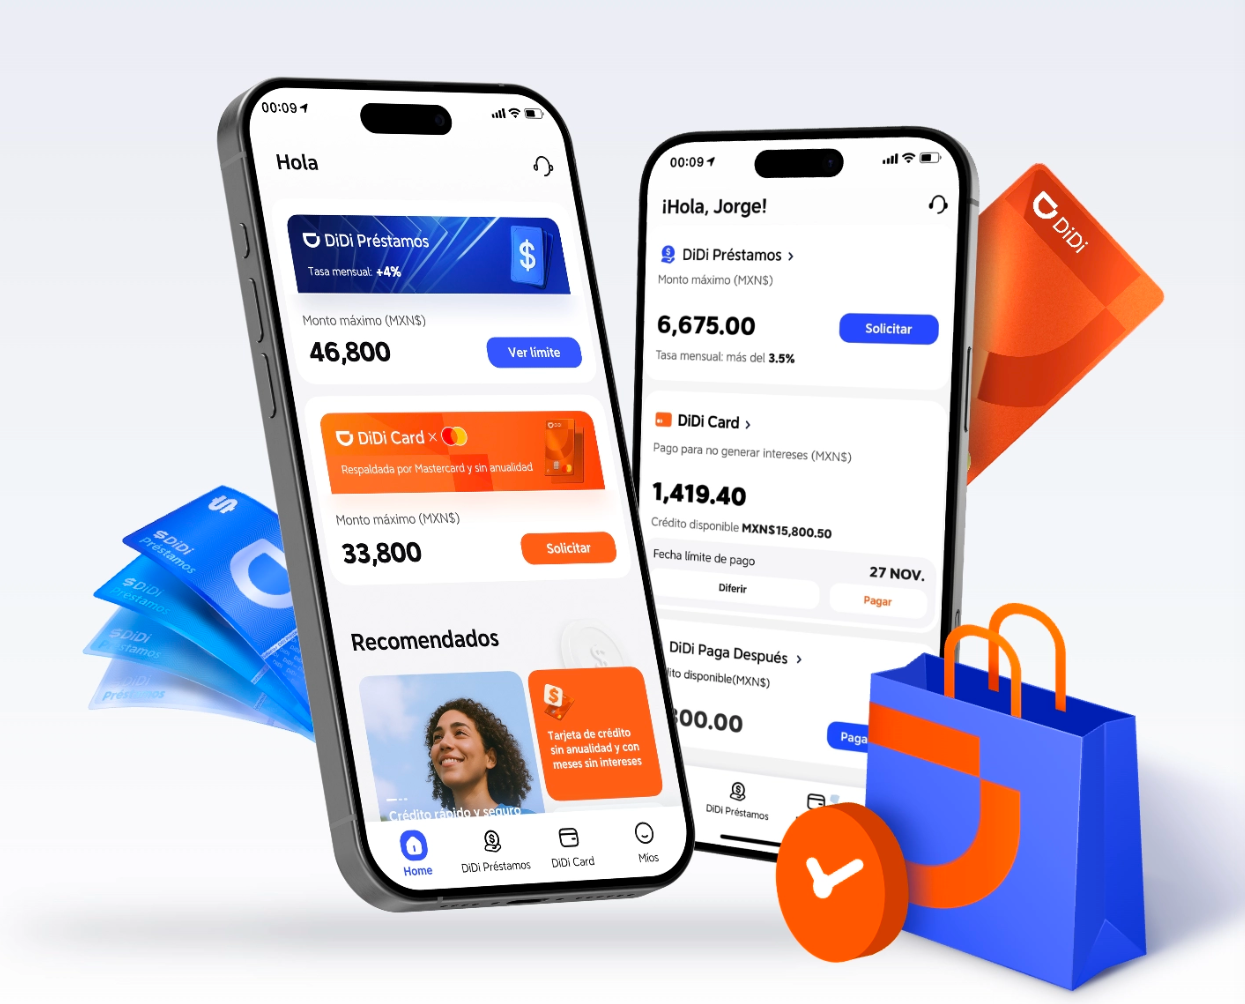
DiDi Finanzas bundles a few core elements: streamlined underwriting, transparent APRs, and an easy-to-use app. The didi finanzas app makes balance checks, repayments and transaction history visible in plain language. For someone juggling irregular income, the revolving credit model lets users draw, repay and draw again up to an approved limit — which beats one-off personal loans on flexibility.
What users often overlook
Common mistakes come down to three things: assuming any credit is cheap, ignoring billing cycles, and skipping small-term planning. People sometimes treat a revolving line like free money — but interest accrues if you carry a balance, and fees can add up. A heads-up: watch the billing period, and map repayments to your cash flow. Little habits — like scheduling repayments right after paydays — help avoid surprise interest.
Where it wins and where it doesn’t
Strengths are speed and convenience. Compared to traditional banks, onboarding is faster and documentation requirements are lighter. That said, if you need a very large, long-term loan for something like a home purchase, a specialised mortgage or term loan is still the right tool. Think of DiDi Finanzas as a practical, short-to-medium term credit solution — great for smoothing income, funding repairs, or managing seasonal expenses.
Alternatives worth considering
Not every wallet or user profile suits a fintech credit line. Alternatives include secured lines from banks, credit cards with grace periods, or peer-to-peer lenders. Each has trade-offs: secured products may offer lower rates but require collateral; credit cards offer convenience but often carry higher APRs on carried balances. Match the product to the use case — working capital vs. long-term finance — and check how each provider handles risk assessment and customer support.
Practical steps to get started
Start by checking your credit score and recent cash flow. Prepare identity and income records, even if the app asks for minimal documentation — having them ready speeds underwriting. Limit your initial draw to what you can comfortably repay within a month or two, and use the app’s notifications to keep repayments timely. Keep an eye on fees and promotional terms; they can change after the introductory period.
Advisory: three golden rules for choosing revolving credit
1) Prioritise transparency: favour providers that show APR, fees and billing cycle clearly in the app. 2) Match term to need: use revolving credit for short-to-medium gaps, and term loans for planned, long-term purchases. 3) Check flexible repayment options: look for tools like auto-pay, adjustable instalments, and real-time balance updates so you can manage cash flow without surprises. These three metrics give you a quick read on whether a product will fit your life — and protect your pocket.
DiDi Finanzas lines up as a practical option when you need flexible, no-collateral credit that integrates with daily income and payments — useful for gig workers, small traders and anyone who needs a reliable short-term credit line. Trust the numbers, watch the fees, and use the app to keep decisions simple. —